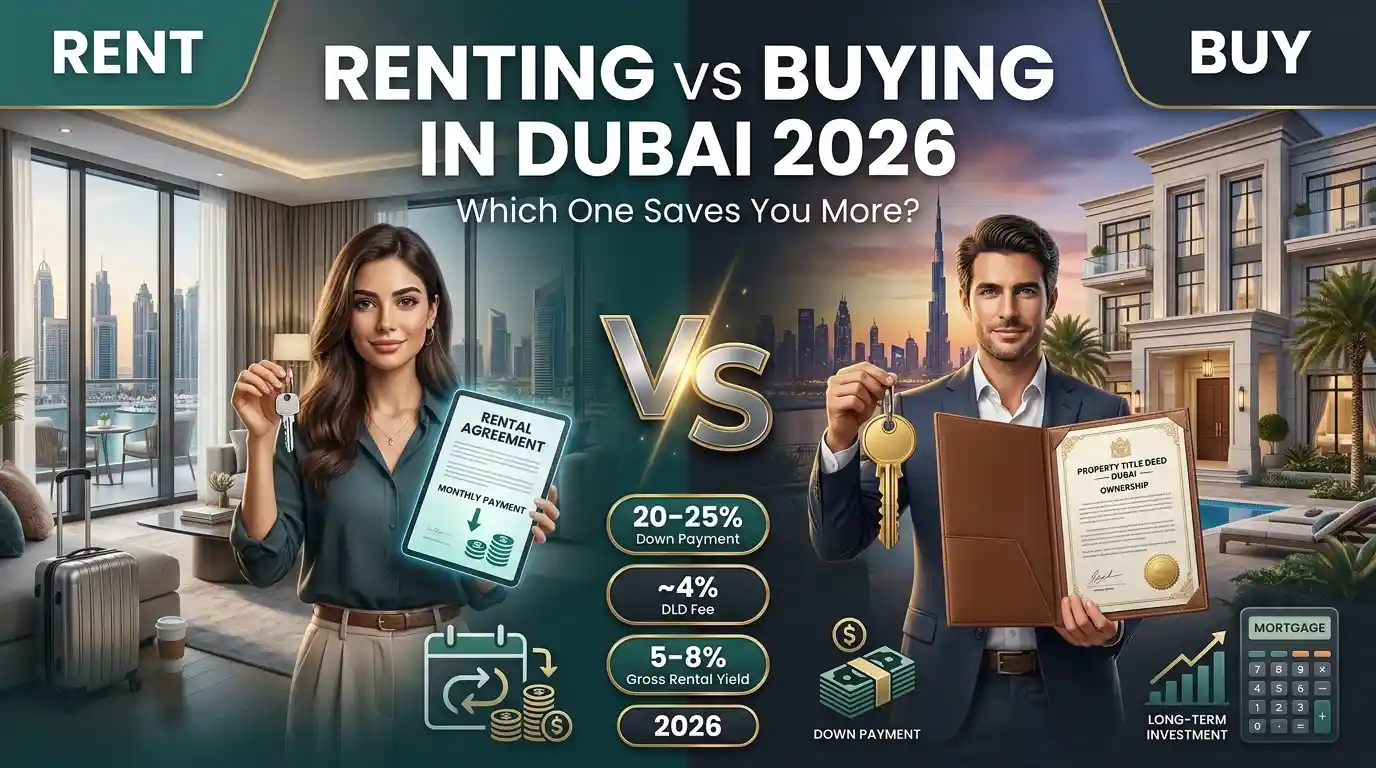
Renting vs Buying in Dubai (2026): Which Saves You More?
Dubai runs one of the more expat-friendly property markets in the world — freehold zones let foreigners own outright, there’s no annual property tax, and gross rental yields regularly beat London, New York, or Singapore. That doesn’t automatically mean buying is the right move for everyone here; renting still dominates the market for good reason. I’ve walked friends and colleagues through this exact decision more times than I can count over the years I’ve lived here, and the honest pattern is almost always the same: it comes down to visa stability and how certain you actually are you’ll still be in this city in five years, not the mortgage math itself.
Overview: How Dubai’s Market Actually Works
Dubai’s property market splits cleanly into two categories that determine whether buying is even an option for you: freehold and non-freehold. Freehold areas — Dubai Marina, Downtown Dubai, Business Bay, Palm Jumeirah, JVC, and dozens of others — allow full foreign ownership. Non-freehold areas, generally older, more traditional neighborhoods like parts of Deira and Bur Dubai, are reserved for UAE and GCC nationals. If you’re an expat weighing renting vs buying in Dubai, this distinction is the very first filter, before rental yields or mortgage rates even enter the conversation.
1. Freehold Zones: Where Expats Can Actually Buy
Ownership in a freehold zone is a full title deed, registered directly with you as the legal owner through the Dubai Land Department (DLD), the government body that regulates every property transaction, rental index figure, and tenancy dispute in the emirate.
2. The Renting Market in Dubai
Most residents in Dubai — including many long-term ones — rent, and the system is built around annual contracts, standardized DLD paperwork, and a rent-cap mechanism that genuinely limits how much a landlord can raise your rent at renewal.
- Annual Contracts: The standard structure, paid via 1-12 post-dated cheques depending on what you negotiate with the landlord.
- Ejari Registration: Every tenancy must be registered on Ejari — it’s what makes your contract legally enforceable and is required to set up DEWA.
- RERA Rental Index: The DLD’s Rental Index caps how much your rent can legally increase at renewal, based on how far below the current market average your rent sits.
- 90-Day Notice Rule: A landlord must give written notice of any rent increase at least 90 days before your contract expires, or the increase doesn’t legally stand.
3. The Buying Market in Dubai
Buying in Dubai splits further into ready (secondary market, move-in ready) and off-plan (bought directly from a developer, usually under construction, paid via a milestone-linked payment plan). Off-plan carries different risk — developer delays, market shifts before handover — but often comes with a lower entry price and a payment plan that spreads cost over years instead of requiring a full mortgage upfront.
| Purchase Type | Typical Structure | Best For |
|---|---|---|
| Ready / Secondary | Full payment or mortgage at purchase | Buyers wanting to move in immediately |
| Off-Plan | Developer payment plan tied to construction milestones | Buyers comfortable waiting, chasing lower entry price |
4. Real Cost Comparison: Renting vs Buying
Take a realistic JVC 1-bedroom as a working example — a genuinely common entry point for both renters and first-time buyers in Dubai.
| Cost Item | Renting (Annual) | Buying (AED 900k, 25% down) |
|---|---|---|
| Base Payment | ~AED 70,000/year rent | ~AED 3,900/month mortgage (25yr, ~4.5%) |
| Upfront Cost | ~AED 3,500-7,000 (agency fee + Ejari) | ~AED 225,000 down payment + ~AED 63,000 fees |
| Annual Housing Fee | Included in DEWA (5% of annual rent) | 5% of notional annual rental value via DEWA |
| Service Charges | Not applicable | ~AED 8,000-15,000/year, building-dependent |
| Maintenance | Landlord’s responsibility | Owner’s responsibility |
5. Mortgages for Expats in Dubai
- Down Payment: UAE Central Bank regulations require a minimum 20-25% down payment for expats on properties under AED 5 million, and a larger share for properties above that threshold.
- Loan Term: Commonly capped at 25 years, or until the borrower turns 65-70 depending on the bank.
- Income Requirements: Banks typically want debt-to-income ratios under roughly 50%, factoring in the new mortgage payment alongside existing obligations.
- Salaried vs Self-Employed: Salaried applicants usually clear approval faster; self-employed and freelance-visa applicants often face more documentation requirements.
6. Rental Yields: Why Dubai Attracts Investors
Gross rental yields in many established Dubai communities commonly run 5-8%, meaningfully higher than mature global markets like London (often 3-4%) or Hong Kong (often under 3%). Higher-yield areas tend to be value-oriented communities like JVC, International City, and Dubai South, while premium areas like Palm Jumeirah and Downtown often trade lower yields for stronger long-term capital appreciation potential.
7. Buying Property and the Golden Visa
Property investment above a set threshold can qualify a buyer for a UAE Golden Visa — a long-term residency status (commonly 10 years) that isn’t tied to a specific employer, unlike a standard employment visa. This is one of the genuine non-financial reasons buying appeals to some long-term expats even when the pure rent-vs-buy math is close: the visa stability itself has real value beyond the property’s cash flow.
8. Pros & Cons of Buying in Dubai Specifically
✅ Pros
- No annual property tax
- Full foreign ownership in freehold zones
- Rental yields well above many mature global markets
- Golden Visa eligibility above the investment threshold
- DLD-regulated, relatively transparent transaction process
⚠️ Cons
- Ownership doesn’t guarantee your UAE residency — visas are typically tied to a job, not the property, below the Golden Visa threshold
- Off-plan carries developer/completion risk
- Service charges vary widely and can erode net yield
- Resale liquidity varies significantly by community and market cycle
9. Common Mistakes When Renting or Buying in Dubai
Frequently Asked Questions
Yes — in designated freehold zones, foreigners can hold full, outright ownership of property, unlike in non-freehold areas reserved for UAE/GCC nationals.
No annual property tax exists in Dubai, though a one-time DLD transfer fee (commonly 4% of the purchase price) applies at registration.
Typically 20-25% for a first property under AED 5 million, per UAE Central Bank mortgage cap regulations for expat buyers.
Increases are capped by the RERA Rental Index — if your current rent is close to the market average, no increase is permitted; the further below average, the higher the allowed increase, up to a set ceiling.
Gross rental yields in many established communities commonly range from 5-8%, notably higher than mature markets like London or New York.
Yes — every tenancy contract must be registered on Ejari, and it’s required to set up DEWA, apply for some visas, and enforce your tenancy rights.
Some banks offer non-resident mortgages, but terms are stricter, typically requiring a larger down payment and higher income proof than resident mortgages.
The DLD transfer fee (commonly 4%), a DLD admin fee, agency commission (commonly 2%), mortgage registration fee if financed, and the down payment itself.
Yes — property investment above a set threshold can qualify a buyer for a UAE Golden Visa, a long-term residency option tied to real estate investment.
A cash purchase can complete in as little as a few weeks; a financed purchase typically takes longer once mortgage approval and valuation are factored in.
Yes — an annual DEWA housing fee (5% of the notional annual rental value) and building/community service charges, which vary significantly by development.
Dubai remains predominantly a renter’s market overall, though ownership has grown steadily as freehold zones expanded and mortgage products for expats matured.
It’s possible but usually involves a penalty clause in the tenancy contract, commonly requiring notice and a payment equivalent to a portion of remaining rent.
The bank can pursue legal foreclosure proceedings through the Dubai courts, which can result in the property being sold to recover the outstanding loan.
Yes — off-plan purchases are usually paid via a developer payment plan tied to construction milestones, carry different risk, and are regulated separately through DLD’s escrow account rules.
- Reviewed by the NearbyFinders Real Estate & Housing Team.
- Rental index mechanics and transaction process cross-checked against the official Dubai Land Department at the time of writing — always confirm current fees, caps, and mortgage LTV rules directly via dubailand.gov.ae or a licensed UAE bank.
- This guide is for general informational purposes only and is not financial or legal advice.
Written & Reviewed by Asad Bukhari
Asad moved to Dubai over 20 years ago to work as a newspaper reporter covering city and relocation news, and has been reporting on the city ever since. Over the years he expanded that first-hand knowledge of Dubai’s neighbourhoods and relocation process into his own real estate business, which he still runs today. This guide draws on both his journalism background and his hands-on property experience.
Pingback: Driver Jobs in Dubai 2026: Salaries, UAE License & How to Apply