UAE Mortgage Guide (2026): LTV Rules, Rates, Fees & How to Apply
Most “how much down payment do I need in the UAE” answers you’ll find online are rough guesses. The actual number is set in black and white by the UAE Central Bank’s mortgage regulations — a fixed Loan-to-Value cap that depends on your nationality, whether it’s your first property, and whether the price sits above or below AED 5 million. This guide walks through those exact figures, how EIBOR-linked rates work, what a bank actually checks before approving you, and the full application process from pre-approval to key handover. I’ve sat through this process myself, and the single biggest gap between what people expect and what a bank actually offers is almost always the LTV cap — assuming 20% down when the real regulatory minimum for their situation is closer to 25% or more.
Overview: How UAE Mortgage Regulation Works
Every bank and finance company offering mortgage loans in the UAE operates under a single regulatory framework set by the UAE Central Bank’s Regulations Regarding Mortgage Loans, first issued in 2013 and amended several times since. Two numbers from that framework matter more than anything a bank’s marketing page will tell you: your maximum Loan-to-Value (LTV) ratio, and your maximum Debt Burden Ratio (DBR). Both are hard regulatory caps, not negotiable bank policy — no lender can offer you better terms than the Central Bank ceiling allows, no matter how strong your application looks.
1. Loan-to-Value (LTV) Rules: The Real Numbers
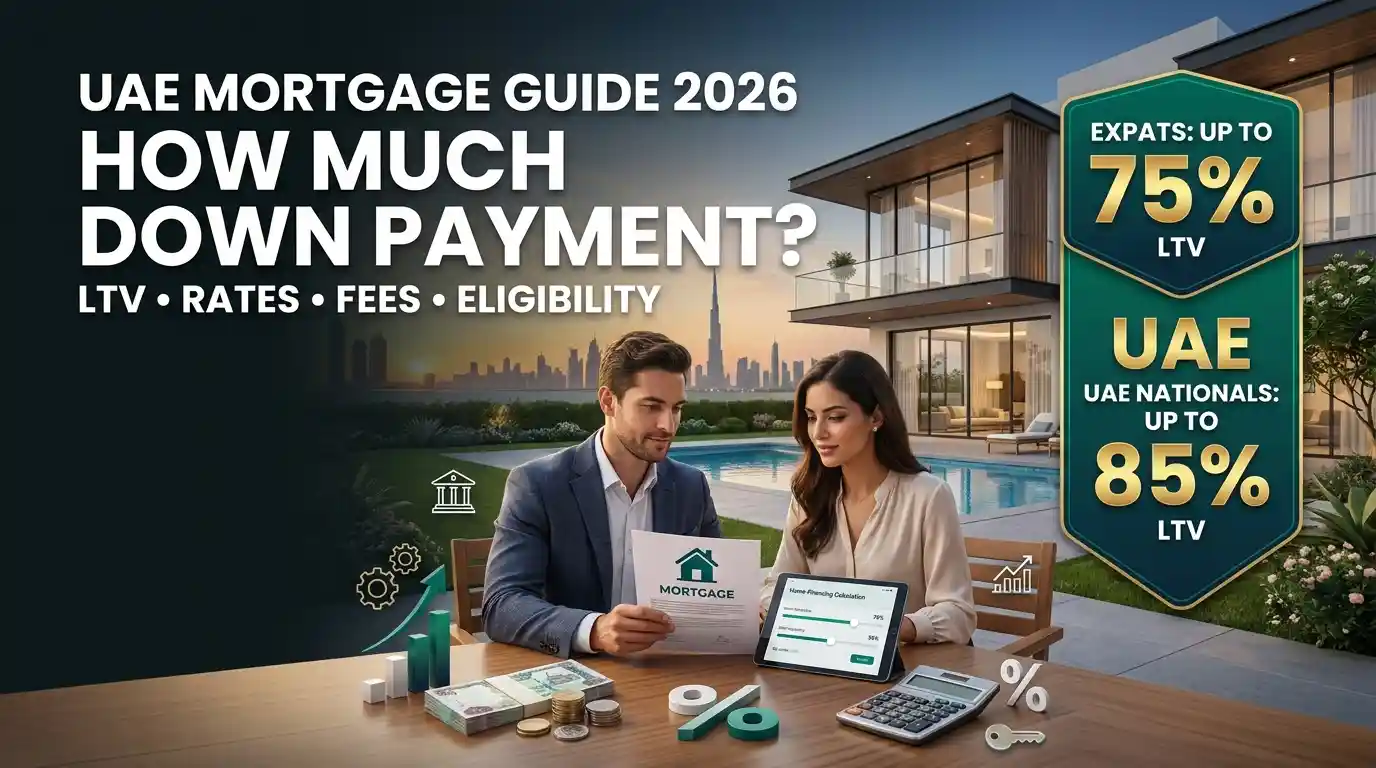
The Central Bank sets different maximum LTV ratios based on nationality, whether it’s your first residential property, and the property’s value relative to a AED 5 million threshold.
| Buyer Category | Property ≤ AED 5 Million | Property > AED 5 Million |
|---|---|---|
| UAE National — First Home | Up to 85% | Up to 75% |
| UAE National — Second/Investment Property | Up to 65% | Up to 65% |
| Expatriate — First Home | Up to 75% | Up to 65% |
| Expatriate — Second/Investment Property | Lower cap applies (bank-specific within regulatory ceiling) | Lower cap applies |
In practical terms: an expat buying their first home for AED 1.5 million can typically borrow up to 75% (AED 1,125,000), meaning a minimum down payment of roughly AED 375,000 — not the 20% many first-time buyers assume going in.
2. Debt Burden Ratio (DBR)
DBR caps how much of your gross monthly income can go toward total debt repayments — including the new mortgage payment alongside any existing loans, credit cards, or other financing. The Central Bank generally sets this ceiling around 50% of income, though it can rise to 60% for certain government-guaranteed local housing programs for UAE nationals. Banks calculate this using your salary certificate and existing liability statements, and it’s a hard cap they cannot lend beyond regardless of how much collateral or down payment you’re offering.
3. Interest Rates: Fixed vs EIBOR-Linked
- Fixed-Rate Introductory Period: Many banks offer a fixed rate for the first 1-5 years, giving payment predictability while you settle into the mortgage.
- EIBOR-Linked Variable Rate: After the fixed period, most mortgages revert to a variable rate tied to EIBOR (Emirates Interbank Offered Rate) plus a bank margin, meaning your payment can rise or fall with the broader rate environment.
- Islamic (Shariah-Compliant) Financing: Structures like Ijara (lease-to-own) or Murabaha (cost-plus sale) are widely available and follow the same Central Bank LTV framework as conventional mortgages.
4. Fees Beyond the Down Payment
5. Eligibility Criteria
6. Documents Required
7. How to Apply: Step by Step
Pre-approval is worth getting before you seriously start property hunting — it tells you your real borrowing capacity, not a rough estimate, and gives sellers confidence you’re a qualified buyer when you make an offer.
8. Common Mistakes to Avoid
Frequently Asked Questions
Per UAE Central Bank regulations, expats can typically borrow up to 75% of the property value for a first home valued at AED 5 million or less, and up to 65% for properties above that threshold.
UAE nationals can typically borrow up to 85% of the property value for a first home valued at AED 5 million or less, and up to 75% above that threshold, with a lower cap for second/investment properties.
DBR is the Central Bank-mandated limit on how much of your monthly income can go toward total debt repayments, commonly capped around 50% including the new mortgage.
Some banks offer non-resident mortgage programs, but terms are typically stricter, with a larger down payment requirement and more extensive income documentation.
Terms commonly run up to 25 years, though most banks cap the term so the loan is repaid by a set retirement age, often around 65-70.
Both are available — many banks offer an initial fixed-rate period (commonly 1-5 years) before reverting to a variable rate tied to EIBOR.
Salary certificate, recent bank statements, Emirates ID, passport with valid visa, and the property’s title deed or sale agreement.
A conditional confirmation from a bank of how much you can borrow, based on your income and debt profile, before you’ve selected a specific property.
Yes — a mortgage registration fee, bank processing fee, property valuation fee, and often life/property insurance premiums required by the lender.
Yes, but typically with more extensive documentation requirements — audited financials, trade license, and a longer income history than salaried applicants.
The bank can pursue legal foreclosure proceedings through the UAE courts, which can ultimately result in the property being sold to recover the outstanding loan.
Yes, but Central Bank LTV limits are lower for second/investment properties than for a first home, since regulators treat investment lending as higher risk.
Yes — many UAE banks offer Shariah-compliant home finance structures (such as Ijara or Murabaha) that follow the same Central Bank LTV framework as conventional mortgages.
Yes — refinancing (switching lenders for better terms) is commonly available, though early settlement fees on the original loan should be checked before switching.
- Reviewed by the NearbyFinders Real Estate & Housing Team.
- LTV and DBR figures sourced directly from the UAE Central Bank’s published Rulebook (Regulations Regarding Mortgage Loans) at the time of writing — always confirm current figures via rulebook.centralbank.ae or a licensed UAE bank before applying.
- Personal notes are illustrative, drawn from commonly reported first-time buyer experiences rather than one specific verified case file.
- Last updated: July 2026. This guide is for general informational purposes only and is not financial or legal advice.
Pingback: Ejari Registration Guide (2026): How to Register Your Tenancy Contract in Dubai
Pingback: Best Areas to Live in Dubai (2026): Complete Neighborhood Guide